
Table of Contents
CME-2B: Saudi Capital Market Rules and Regulations – Compliance and Anti-Money Laundering
Explore syllabus-aligned study tools, realistic practice and course-grounded AI support.
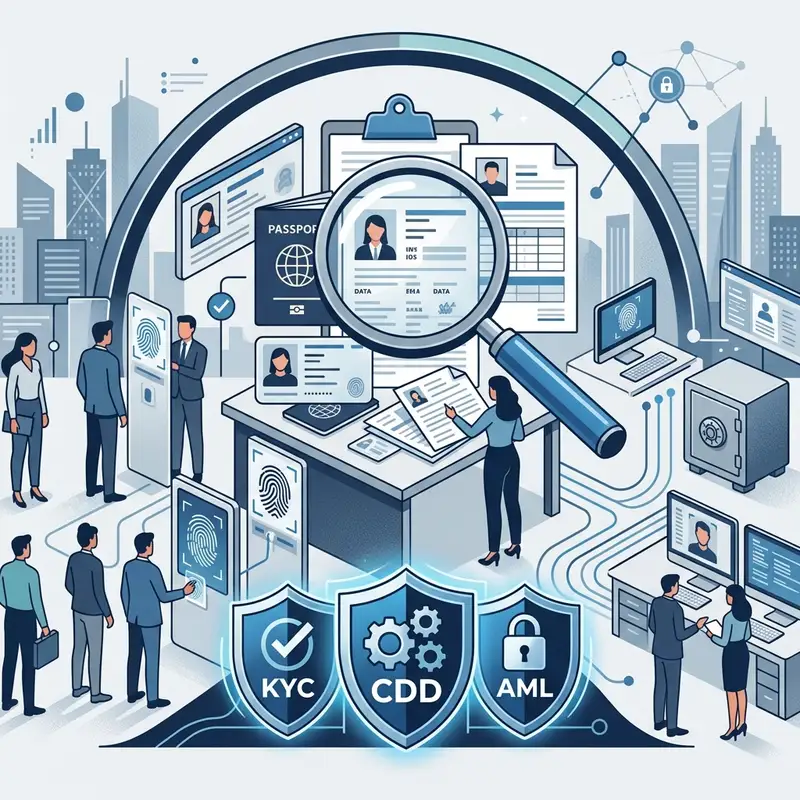
For professionals preparing for the CISI Combating Financial Crime (CAML CME-2B) exam, understanding the mechanics of Customer Due Diligence (CDD) is absolutely paramount. It is the first line of defense in the global fight against money laundering and terrorist financing.
This article breaks down the operational realities of CDD, specifically tailored to the exam’s syllabus requirements.
The Three Tiers of Due Diligence
Not all clients pose the same risk, and therefore, not all clients require the same level of scrutiny. The risk-based approach dictates three levels of diligence:
1. Simplified Due Diligence (SDD)
Used for low-risk scenarios. For example, if the client is another regulated financial institution or a publicly listed company on a major exchange. The identity is already largely verified by public records or other regulators.
2. Standard Customer Due Diligence (CDD)
The baseline requirement for most clients. It involves:
- Identifying the customer.
- Verifying their identity using reliable, independent source documents.
- Understanding the nature and purpose of the intended business relationship.
3. Enhanced Due Diligence (EDD)
Required for high-risk situations. Exam questions will heavily test your ability to trigger EDD. Triggers include:
- The client is a Politically Exposed Person (PEP).
- The client is located in a high-risk jurisdiction (e.g., FATF grey/black lists).
- Complex, unusually large transactions with no obvious economic purpose.
Free CME-2B: Saudi Capital Market Rules and Regulations – Compliance and Anti-Money Laundering Practice Questions & Exam Preview
Try 15 CME-2B: Saudi Capital Market Rules and Regulations – Compliance and Anti-Money Laundering practice questions from AML/CFT and Customer Due Diligence
Practice CME-2B: Saudi Capital Market Rules and Regulations – Compliance and Anti-Money Laundering exam questions with answers and explanations. The full course includes 5 mock exams and complete syllabus coverage.
Exam Preview
In the context of money laundering, what does the 'Layering' stage involve?
Flashcards
What are the notification timeframes for a CEO resignation?
Focus Learn
- Timelines for CMA notification (within 2 days for CEO resignation, 7 days for other material changes, 30 days for address/structural changes).
- Conditions surrounding the cancellation or withdrawal of authorisation.
- Requirements for the safe custody of client assets and regular client statements.
- Close Links — 30 days' advance notice before establishing.
- Approved Persons — CMA approval required for registrable functions.
- Record-keeping obligations — 10-year retention period.
This chapter covers the regulatory framework governing capital market institutions in Saudi Arabia under the Capital Market Authority (CMA). Authorised persons must meet ongoing obligations including notification requirements — for example, notifying the CMA within 2 days of a CEO resignation, within 7 days for other material changes, and within 30 days for certain structural changes such as address or name changes and close links. The CMA has the power to cancel or withdraw authorisation if conditions are breached. A central focus is the safe custody of client assets: firms must strictly segregate client money from their own funds, maintain proper records, and provide regular client statements. Client money cannot be pooled with firm money under any circumstances, even temporarily. The ch…
Unlock all Focus Learn
Open every chapter’s key areas, pitfalls, exam traps and key numbers.
Unmasking the Ultimate Beneficial Owner (UBO)
UBO analysis must reach the natural person who ultimately owns or controls the entity under the applicable rule. Calculate each ownership chain before aggregating paths: 60% of Holding A multiplied by Holding A’s 60% of the customer is a 36% indirect interest, not 60%. Test control separately because voting agreements or appointment powers can matter even where the multiplied ownership is lower; do not import a threshold from another jurisdiction without checking the governing rule.
Conclusion
The exam will test your practical application of these rules. Memorizing definitions is not enough; you must be able to read a scenario and correctly identify whether Standard or Enhanced due diligence is required.
Frequently Asked Questions
1 When is Enhanced Due Diligence (EDD) required?
EDD is required for high-risk clients, such as Politically Exposed Persons (PEPs) or clients from high-risk jurisdictions.
2 What is an Ultimate Beneficial Owner (UBO)?
A UBO is the natural person who ultimately owns or controls a legal entity, typically defined by a percentage ownership threshold (e.g., 25%).
3 What is the difference between KYC and CDD?
KYC (Know Your Customer) is the broader principle of understanding the client, while CDD (Customer Due Diligence) refers to the specific operational checks and identity verifications performed.
Keep learning
Related Insights
CAML CME-2B: The Guide to Suspicious Activity Reporting (SAR)
A technical guide to the MLRO, SAR triggers, and tipping off for the CISI SCMR CAML CME-2B exam.
CMA Saudi Compliance Training for Companies: A Comprehensive Guide
Ensure your team is fully certified. Explore our B2B compliance training solutions for the Saudi Capital Market (CME-2B) and SCMR CAML.
Saudi CMA CME-2 Certification Guide 2026: Compliance & AML Exams
Your complete guide to the Saudi Capital Market Authority (CMA) CME-2 Compliance and AML certification for 2026. Get exam dates, fees, passing scores, and mock exams.
Ready to Prepare for Your Exam?
Prepare with syllabus-aligned study tools, realistic practice and course-grounded AI support.
Explore Courses