Table of Contents
CME-4A: Wealth & Investment Management
Explore syllabus-aligned study tools, realistic practice and course-grounded AI support.
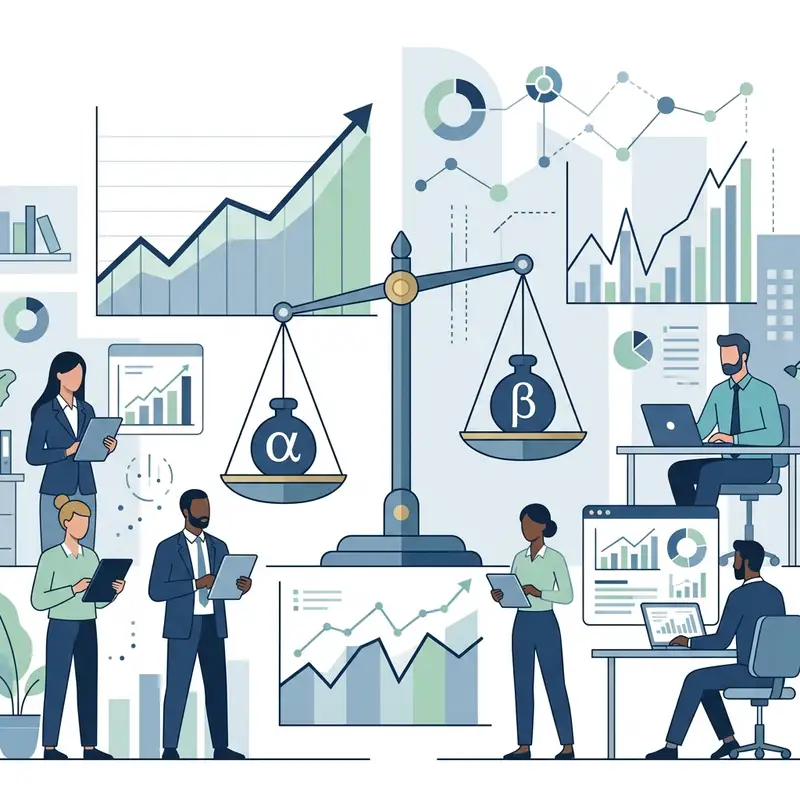
The capstone of the CISI ICWIM CME-4A syllabus is Portfolio Management and Performance Measurement. After understanding asset classes and regulations, a wealth manager must be able to construct a portfolio and objectively measure whether it is performing well relative to the risk being taken.
This article breaks down the statistical Greek letters—Alpha and Beta—and the core ratios that will appear on your exam.
Understanding Risk
Before you can measure performance, you must understand risk.
- Systematic Risk (Market Risk): The risk inherent in the entire market (e.g., a global recession, interest rate hikes). It cannot be diversified away.
- Unsystematic Risk (Specific Risk): The risk associated with a specific company or sector (e.g., a CEO scandal at a tech company). It can be eliminated through diversification.
Standard Deviation is the most common measure of total risk (both systematic and unsystematic). It measures the volatility of a portfolio’s returns. A high standard deviation means the portfolio’s value fluctuates wildly; a low standard deviation indicates steady, predictable returns.
Alpha and Beta Explained
The ICWIM exam heavily tests your understanding of these two metrics.
Beta (Market Sensitivity)
Beta measures a portfolio’s systematic risk—how much it moves in response to the broader market. The market itself always has a Beta of exactly 1.0.
- A Beta of 1.2 means the portfolio’s excess return is estimated to move 1.2 times the market’s excess return within the model. It does not guarantee a 12% fall whenever the market falls 10%.
- A Beta of 0.8 indicates lower estimated market sensitivity, but the portfolio can still have substantial company-specific or other non-market volatility.
Alpha (Manager Skill)
Alpha is the return left unexplained by the chosen benchmark or pricing model after allowing for market exposure. A positive alpha depends on the benchmark, period and inputs; it is not proof by itself that stock selection or timing skill caused the result.
Free CME-4A: Wealth & Investment Management Practice Questions & Exam Preview
Try 15 CME-4A: Wealth & Investment Management practice questions from Collective Investments and Funds
Practice CME-4A: Wealth & Investment Management exam questions with answers and explanations. The full course includes 5 mock exams and chapter study tools.
Exam Preview
An ETF gains index exposure through a swap rather than holding all constituents. What additional exposure deserves attention?
Flashcards
What is the investment chain?
Focus Learn
- Functions of the financial services sector and the investment chain
- Differences between wholesale and retail financial markets
- Roles of retail banks, investment banks, pension funds, fund managers, custodians
- Distinction between discretionary and advisory investment management
- Wealth management providers and the role of platforms
- Impact of technology on financial services (robo-advisers, RegTech)
This chapter forms the foundation of the ICWIM qualification by exploring how the financial services sector is structured and why it exists. At its core, the sector serves three fundamental purposes: channelling money from those who have surplus capital (investors/savers) to those who need it (borrowers), enabling the transfer and management of risk through products like insurance and derivatives, and providing settlement and payment systems. The 'investment chain' is the central concept — it describes how money flows from individual investors through intermediaries (such as fund managers, custodians, platforms and pension schemes) to businesses and governments who need capital. Understanding each link in this chain is essential.
The chapter distinguishes between wholesale markets (where…
Unlock all Focus Learn
Open every chapter’s key areas, pitfalls, exam traps and key numbers.
The Sharpe Ratio
Clients don’t just care about raw returns; they care about how much risk the manager took to achieve them. The Sharpe ratio allows that comparison only when return period, risk-free rate, currency and data treatment are consistent.
The Sharpe Ratio calculates this risk-adjusted return. It takes the portfolio’s return, subtracts the risk-free rate to find the excess return, and divides that by standard deviation. A higher positive ratio is generally preferable on a like-for-like basis, but comparisons can mislead when periods, currencies or return distributions differ.
Conclusion
When tackling performance measurement questions, don’t let the math intimidate you. The ICWIM exam focuses more on the interpretation of these metrics than complex calculations. Know what the metrics represent, and you’ll easily identify the correct answers.
Frequently Asked Questions
1 What is the difference between Alpha and Beta?
Beta measures a portfolio's sensitivity to market movements (systematic risk), while Alpha measures the excess return generated by the fund manager above the benchmark.
2 What does the Sharpe Ratio measure?
The Sharpe Ratio measures risk-adjusted return. It tells you how much excess return you are receiving for the extra volatility you endure.
3 What is standard deviation?
Standard deviation is a statistical measure of volatility, representing the degree to which a fund's returns fluctuate around its average return over time.
Keep learning
Related Insights
Demystifying CISI ICWIM CME-4A: Core Asset Classes Explained
Master the differences between equities, bonds, and derivatives for the CISI ICWIM CME-4A exam. Essential study guide with mock questions and flashcards.
CISI ICWIM CME-4A: Investment Funds and Structures Explained
Master the differences between OEICs, Unit Trusts, and Investment Trusts for the CISI ICWIM CME-4A exam. Essential guide with interactive mock questions.
CME-4 Exam Guide: Saudi CMA Wealth Management & Asset Managers Certification
Complete guide to the Saudi CMA CME-4A (Wealth Management) and CME-4B (Asset Managers) exams. Master the syllabus, regulations, and pass on your first attempt.
Ready to Prepare for Your Exam?
Prepare with syllabus-aligned study tools, realistic practice and course-grounded AI support.
Explore Courses