
Table of Contents
CME-1B: Saudi Capital Market Rules and Regulations – General
Explore syllabus-aligned study tools, realistic practice and course-grounded AI support.
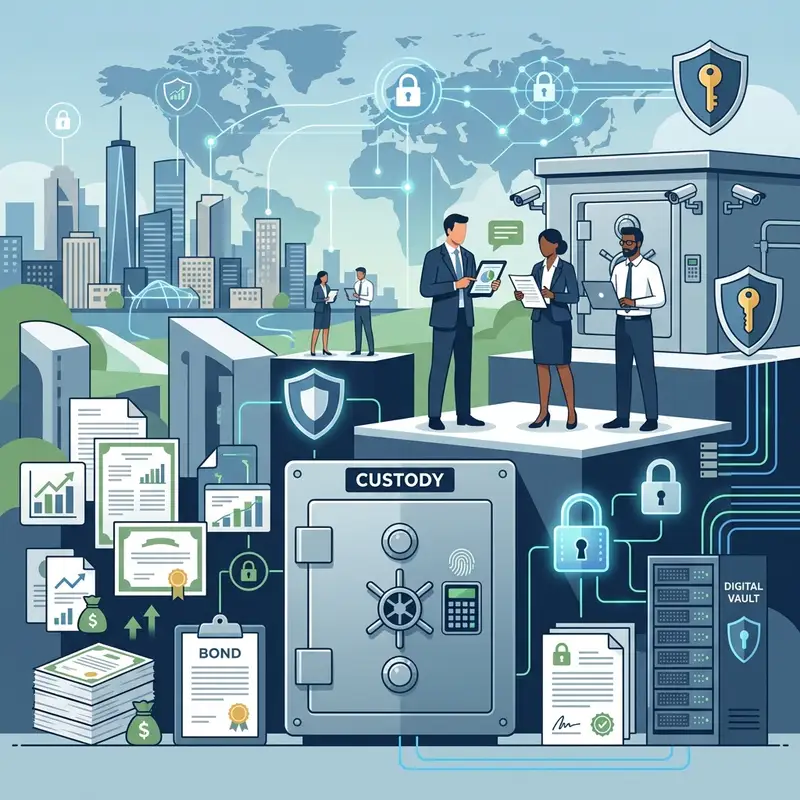
CME-1B is the Saudi Capital Market Rules and Regulations (General Chapter) paper. Older learning material uses General Saudi Capital Market Rules and Regulations (GSCMR). Custody and Safekeeping of Assets belongs within its institutional and client-protection framework; the FA publishes eight chapter weights rather than a separate high-weight custody paper.
This guide connects account structures with the Saudi Capital Market Institutions Regulations, especially Articles 69–70 and 84–90. Learn how ownership, holding arrangements, client disclosures and records work together rather than assuming that a general nominee-account description establishes the local rule.
The Role of the Custodian
A custodian safeguards and administers assets under the applicable custody agreement. A custody mandate should not be confused with authority to make investment decisions. CMIR Article 88 requires written custody terms addressing registration, instructions, liability, fees, income, corporate actions and pooling.
Depending on the agreed service and applicable rules, administrative tasks can include:
- Safekeeping of physical and electronic securities.
- Settlement of trades.
- Processing corporate actions (dividends, voting rights).
- Collection of dividends and other entitlements under the agreement.
Nominee Accounts: Pooled vs. Designated
A nominee arrangement separates the name in which assets are held from the underlying client’s entitlement. It is not a universal rule that a Saudi investor’s shares will be registered in a broker-controlled nominee company’s name. CMIR Article 85(c) starts from registration in the client’s name, including the underlying client where another CMI acts for its own client. Securities eligible for the Depositary Centre must be held there according to its rules.
Article 85(d)–(e) addresses registration in the institution’s name in accordance with the Depository Centre Rules, or an overseas custodian’s name for securities acquired overseas. It requires advance written risk disclosure, prior written client approval and records distinguishing each client’s assets from the institution’s and other clients’ assets. Use those conditions when comparing the two structures below:
1. Pooled (Omnibus) Nominee Accounts
In an omnibus account, the assets of many different clients are grouped together into a single account at the registry level.
- Pro: Pooling can reduce account-administration work; actual costs depend on the arrangement.
- Con: Under Annex 5.2 item 20, a retail client must receive an explanation of pooling and warnings about non-separately-identifiable holdings and possible pro rata participation in an irreconcilable shortfall caused by custodian default. Accurate individual-entitlement records remain necessary.
2. Designated Nominee Accounts
In this structure, the account carries a reference identifying a particular client’s holdings. A reference such as XYZ Nominees Ltd <Account Client A> is an illustration of designation; it does not replace Article 85’s requirements for the legal registration actually used.
- Pro: A separate reference can make operational identification of the particular client’s holdings easier.
- Con: Designation still requires correct title, records and reconciliations. Costs vary, and a label alone does not guarantee return of assets after a failure.
The native 15-question, 10-flashcard and summary preview below illustrates the broader CME-1B course format. It is not a custody-only test. The full course has five 50-question, 60-minute mocks, with 200 distinct questions in Mocks 1–4 and a mixed fifth that reuses earlier items.
Free CME-1B: Saudi Capital Market Rules and Regulations – General Practice Questions & Exam Preview
Try 15 CME-1B: Saudi Capital Market Rules and Regulations – General practice questions from Securities Business and Capital Market Institutions
Practice CME-1B: Saudi Capital Market Rules and Regulations – General exam questions with answers and explanations. The full course includes 5 mock exams and chapter study tools.
Exam Preview
Which of the following lists correctly identifies the five types of securities business activities?
Flashcards
What is the Capital Market Authority (CMA)?
Focus Learn
- Capital Market Law establishment: Royal Decree M/30 dated 2/6/1424H (31 July 2003).
- CMA independence and direct reporting line to the Prime Minister.
- Definitions of securities (4 types) vs. non-securities (7 excluded instruments).
- CMA trading suspension powers: 1 day independent, >1 day requires Minister of Finance approval.
- Committee for Resolution of Securities Disputes: composition, appointment, and jurisdiction.
- Dispute timeline: 90-day filing wait, 14-day consideration start, 30-day appeal window.
- Securities Depository Center: sole registration entity, preliminary registration in doubtful cases.
- Evidence admissibility in all forms including electronic, recordings, fax, and email.
The Saudi Arabian Capital Markets have informally operated since 1950, but the Capital Market Law (the Law) was formally introduced pursuant to Royal Decree M/30 dated 2/6/1424H (31 July 2003) to create a transparent, fair, and regulated market. The Law established the Capital Market Authority (CMA) as a fully independent government organisation that reports directly to the Prime Minister — not to SAMA or any ministry. The CMA's four core objectives are: creating an appropriate investment environment, boosting confidence, reinforcing transparency and disclosure standards, and protecting investors and dealers from illegal acts. Securities under the Law include: (a) convertible and tradeable company shares, (b) tradeable debt instruments issued by companies, government, or public institution…
Unlock all Focus Learn
Open every chapter’s key areas, pitfalls, exam traps and key numbers.
Client Asset Segregation
Keep client money and safe-custody assets separate in the analysis. Cash segregation concerns the designated client-money account and supporting ledgers; securities may instead be registered through a nominee or custodian and require records that identify each client’s entitlement.
CMIR Article 70 provides that properly segregated client money and assets are held for clients and are not the institution’s own money or assets; its creditors have no claim or entitlement to them. Apply that rule to the actual holding arrangement. Articles 84–85 require appropriate account titles and registration, Article 87 requires custodian risk assessment, and Article 90 requires reconciliation and discrepancy handling. Overseas legal arrangements and the disclosed pooling risks remain relevant to recovery.
Conclusion
Understanding custody structures isn’t just about passing the CME-1B exam; it’s about understanding the fundamental plumbing of the financial system. Ensure you are comfortable with the pros and cons of different nominee structures before exam day.
Frequently Asked Questions
1 What is the difference between a pooled and designated nominee account?
A pooled account combines holdings for multiple clients; a designated arrangement identifies holdings for a particular client. In Saudi custody questions, also apply CMIR Article 85's registration requirements and the client records and disclosures required for the actual arrangement. The account label alone does not determine protection.
2 Why is client asset segregation important in the GSCMR syllabus?
CMIR Article 70 treats properly segregated client money and assets as held for clients, outside the institution's own assets, with no entitlement for its creditors. Correct registration, records and reconciliations still matter, and disclosed pooling or overseas-custodian risks must be considered. A client-labelled account is not a guarantee of full recovery.
3 What is the role of a custodian?
A custodian is a financial institution responsible for holding and safeguarding the financial assets of clients to minimize the risk of theft or loss.
Keep learning
Related Insights
GSCMR CME-1B: Corporate Actions and Reconciliations Explained
Master the differences between Mandatory and Voluntary corporate actions for the CISI GSCMR CME-1B exam. Essential guide with interactive flashcards.
How to Prepare for Saudi CME-1B: Regulatory Study Strategy
A focused preparation strategy for the current Saudi CME-1B regulatory exam, covering CMA rules, active recall, scenario practice, and timed mock exams.
Finding a Bilingual CME-1 Tutor in Saudi Arabia
Why finding a bilingual CME-1 tutor for the Saudi CMA regulations is difficult, and how online study platforms offer a better, cost-effective alternative.
Ready to Prepare for Your Exam?
Prepare with syllabus-aligned study tools, realistic practice and course-grounded AI support.
Explore Courses