Table of Contents
- • The Evolution of UAE CMA (formerly SCA) Fund Regulations
- - Why Did the Rules Change?
- • Marketing Foreign Funds: The Current Framework
- - 1. Retail Investors (Public Offering)
- - 2. Professional Investors (Private Placement)
- • Free Zones vs. Mainland
- • Test Your Knowledge
- • Preparing for the CISI UAE FRR
CISI UAE FRR
Explore syllabus-aligned study tools, realistic practice and course-grounded AI support.
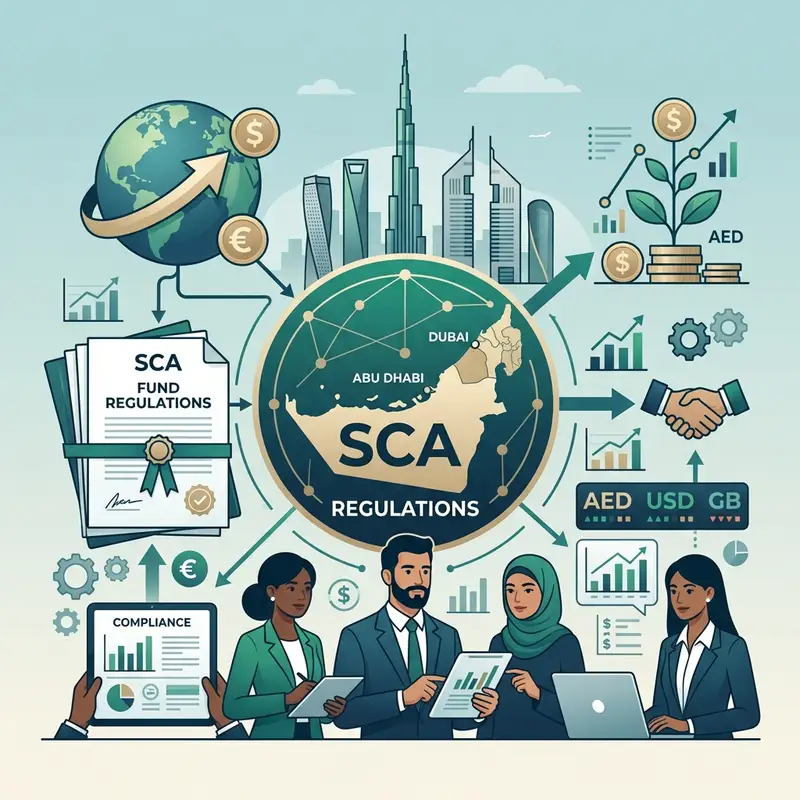
If you operate in the wealth management sector within the United Arab Emirates, understanding the precise regulatory boundaries is critical. Over the past few years, the UAE Capital Market Authority (formerly the Securities and Commodities Authority) (UAE CMA (formerly SCA)) has implemented significant changes regarding how investment products can be marketed to residents.
One of the most consequential shifts involves the marketing and distribution of foreign-owned funds. For professionals preparing for their CISI UAE Financial Rules and Regulations (FRR) exam, mastering these regulations is not just about passing a test—it is about avoiding severe regulatory penalties in your daily practice.
The Evolution of UAE CMA (formerly SCA) Fund Regulations
Historically, the UAE allowed a degree of flexibility in how offshore funds could be marketed locally. However, in recent years, encapsulated in several pivotal decisions by the UAE Capital Market Authority (formerly the Securities and Commodities Authority), the landscape has tightened.
The current framework restricts ordinary foreign funds to private promotion to professional investors after CMA registration and through a licensed local promoter. It does not provide a general public-offer route for an offshore fund to mainland retail investors.
Why Did the Rules Change?
The tightening of regulations was designed to:
- Protect local retail investors from unregulated offshore risks.
- Foster the development of the domestic asset management industry.
- Bring the UAE mainland in line with stringent global compliance standards.
Marketing Foreign Funds: The Current Framework
Under the current UAE CMA (formerly SCA) framework, if a foreign entity wishes to distribute its fund in the UAE mainland, it generally faces two pathways depending on the target audience.
1. Retail Investors (Public Offering)
An ordinary foreign fund cannot be promoted by public offering to mainland retail investors merely by registering it and appointing a promoter. Retail access may instead involve a qualifying mainland feeder fund or a DIFC or ADGM fund using the passporting regime and satisfying its retail conditions; analyse that vehicle separately from private promotion of the offshore fund.
2. Professional Investors (Private Placement)
For professional investors, the foreign fund’s legal representative applies for CMA registration for private promotion, and the promotion is conducted by one or more CMA-licensed local promoters after approval. The current service conditions also impose fund-status and minimum-subscription requirements, so “professional investor” is not a blanket exemption from registration.
Free Zones vs. Mainland
A critical distinction that trips up many finance professionals—and is a frequent topic on the CISI UAE FRR exam—is the jurisdictional boundary between the UAE mainland and the financial free zones.
The UAE CMA (formerly SCA) regulates the mainland. However, the Dubai International Financial Centre (DIFC) is regulated by the Dubai Financial Services Authority (DFSA), and the Abu Dhabi Global Market (ADGM) is regulated by the Financial Services Regulatory Authority (FSRA).
A DFSA-authorised fund is not automatically marketable in mainland Dubai. A DIFC- or ADGM-domiciled fund may use the UAE fund-passporting regime if its conditions are met; otherwise the relevant CMA registration and local-promotion route must be assessed.
Test Your Knowledge
To ensure you understand these critical fund definitions for the exam, test yourself with the interactive flashcards below:
UAE CMA (formerly SCA) Fund Regulation Flashcards
Preparing for the CISI UAE FRR
Understanding the nuances of the UAE Capital Market Authority (formerly the Securities and Commodities Authority)‘s rules on foreign-owned funds is essential for the CISI UAE Financial Rules and Regulations exam. The syllabus heavily weights your understanding of authorized persons, client classification, and the marketing of financial products.
By mastering these rules, you not only prepare yourself for exam success but also equip yourself to operate safely and effectively within the UAE’s fast-growing wealth management sector.
Free CISI UAE FRR Practice Questions & Exam Preview
Try 15 CISI UAE FRR practice questions from Investment Funds
Practice CISI UAE FRR exam questions with answers and explanations. The full course includes 5 mock exams and complete syllabus coverage.
Exam Preview
A private investment fund is preparing a promotional campaign. Which advertising restriction applies to that campaign?
Flashcards
When was the SCA established and where is it headquartered?
Focus Learn
- Establishment and functions of the SCA under Federal Law No. 4 of 2000
- SCA Board: appointed by Cabinet resolution for 4-year terms, renewable once
- Five licence categories and their paid-up capital requirements (AED 30M, 50M, 50M, 5M)
- Corporate governance requirements for PJSCs
- CISI Code of Conduct eight principles
- SCA powers: licensing, investigation, enforcement, penalties
- Related-party transaction 5% threshold requiring General Assembly approval
- Gift restrictions: AED 500 or less for symbolic gifts
- SCA budget timeline: approved 1 month before fiscal year; final accounts within 90 days
1. Regulatory Foundation
This chapter establishes the UAE's regulatory foundation through Federal Law No. 4 of 2000, which created the Securities & Commodities Authority (SCA).
The SCA operates as an independent public authority in Abu Dhabi with its own legal personality, full financial, and administrative independence. It is prohibited from entering into commercial activities, having private interests of its own in any undertaking, or owning/issuing securities.
2. SCA Board & Operations
The SCA is managed by a Board of Directors:
- Constitution: Appointed by resolution of the Cabinet of Ministers.
- Tenure: Members are appointed for 4 years, renewable once only.
- Meetings: The Board must meet at least once every 2 months. Emergency meetings c…
Unlock all Focus Learn
Open every chapter’s key areas, pitfalls, exam traps and key numbers.
Frequently Asked Questions
1 What is the UAE CMA (formerly SCA) rule on foreign-owned funds?
Ordinary foreign funds may be promoted in mainland UAE by private placement to professional investors after CMA registration and through a licensed local promoter. Public promotion of a foreign fund to mainland retail investors is not generally permitted; qualifying UAE, DIFC or ADGM fund structures may use the applicable local or passporting route.
2 Can foreign funds be marketed to professional investors?
Yes, under specific exemptions and private placement rules, foreign-owned funds can be marketed to qualified professional investors and institutional clients, provided the promoter uses a locally licensed entity.
3 Which exam covers the UAE CMA (formerly SCA) fund regulations?
The CISI UAE Financial Rules and Regulations (FRR) exam extensively covers the regulatory framework for investment funds, including both domestic and foreign fund marketing rules.
4 What is the difference between UAE CMA (formerly SCA) and DFSA regarding funds?
The UAE CMA (formerly SCA) regulates the UAE mainland, while the DFSA strictly regulates entities operating within the Dubai International Financial Centre (DIFC) free zone.
5 Do wealth managers need a local promoter?
A local promoter is required for the registered private promotion of a foreign fund to professional investors. It does not turn an ordinary foreign fund into a product that may be publicly offered to mainland retail investors.
Keep learning
Related Insights
UAE CMA (formerly SCA) Licensing Requirements for Financial Analysts in the UAE
A complete guide to UAE CMA (formerly SCA) licensing for Financial Analysts, including CFA equivalency and CISI UAE FRR examination requirements.
UAE CMA (formerly SCA) Licensing Exemptions: A Guide for UAE Finance Professionals
Understand UAE CMA (formerly SCA) licensing exam exemptions and equivalency, including which professional qualifications may be considered and why UAE FRR cannot be replaced.
الدليل الشامل لاجتياز امتحان CISI UAE FRR باللغة العربية
كيف تنجح في امتحان القواعد والأنظمة المالية في الإمارات (UAE FRR) من المرة الأولى؟ استراتيجيات الدراسة، نصائح، ونماذج أسئلة تدريبية باللغة العربية.
Ready to Prepare for Your Exam?
Prepare with syllabus-aligned study tools, realistic practice and course-grounded AI support.
Explore Courses